Financial advice built around your life.
A Personalized Approach to Investment Advice.
Clear advice. Ongoing communication. long-term relationships
Attached to PEAK Investment Services Inc.
The advisors featured on this website are independent representatives attached to PEAK Investment Services Inc. While the advisors provide personalized financial advice, all investment product recommendations are made and processed through PEAK Investment Services Inc., in accordance with regulatory requirements. PEAK Investment Services Inc. is a mutual fund dealer registered with the Canadian Investment Regulatory Organization (CIRO). Its activities include the distribution and supervision of investment products such as mutual funds and ETFs. PEAK’s responsibility is limited solely to the investment products it distributes. Any other services, including financial planning and insurance, are provided by Joshua Bryant and are not the responsibility of PEAK Investment Services Inc.
Commissions, trailing commissions, management fees and expenses may all be associated with mutual fund investments. Mutual funds are not guaranteed, their values change frequently, and past performance may not be repeated. Please read the prospectus and Fund Facts carefully before investing. The information contained on this website is provided for general information purposes only and does not constitute investment advice. The information is not intended to provide specific financial, legal, accounting or tax advice and should not be relied upon in that regard. Investment decisions should be made based on your individual circumstances in consultation with a Mutual Fund Representative.
Where to Find Us
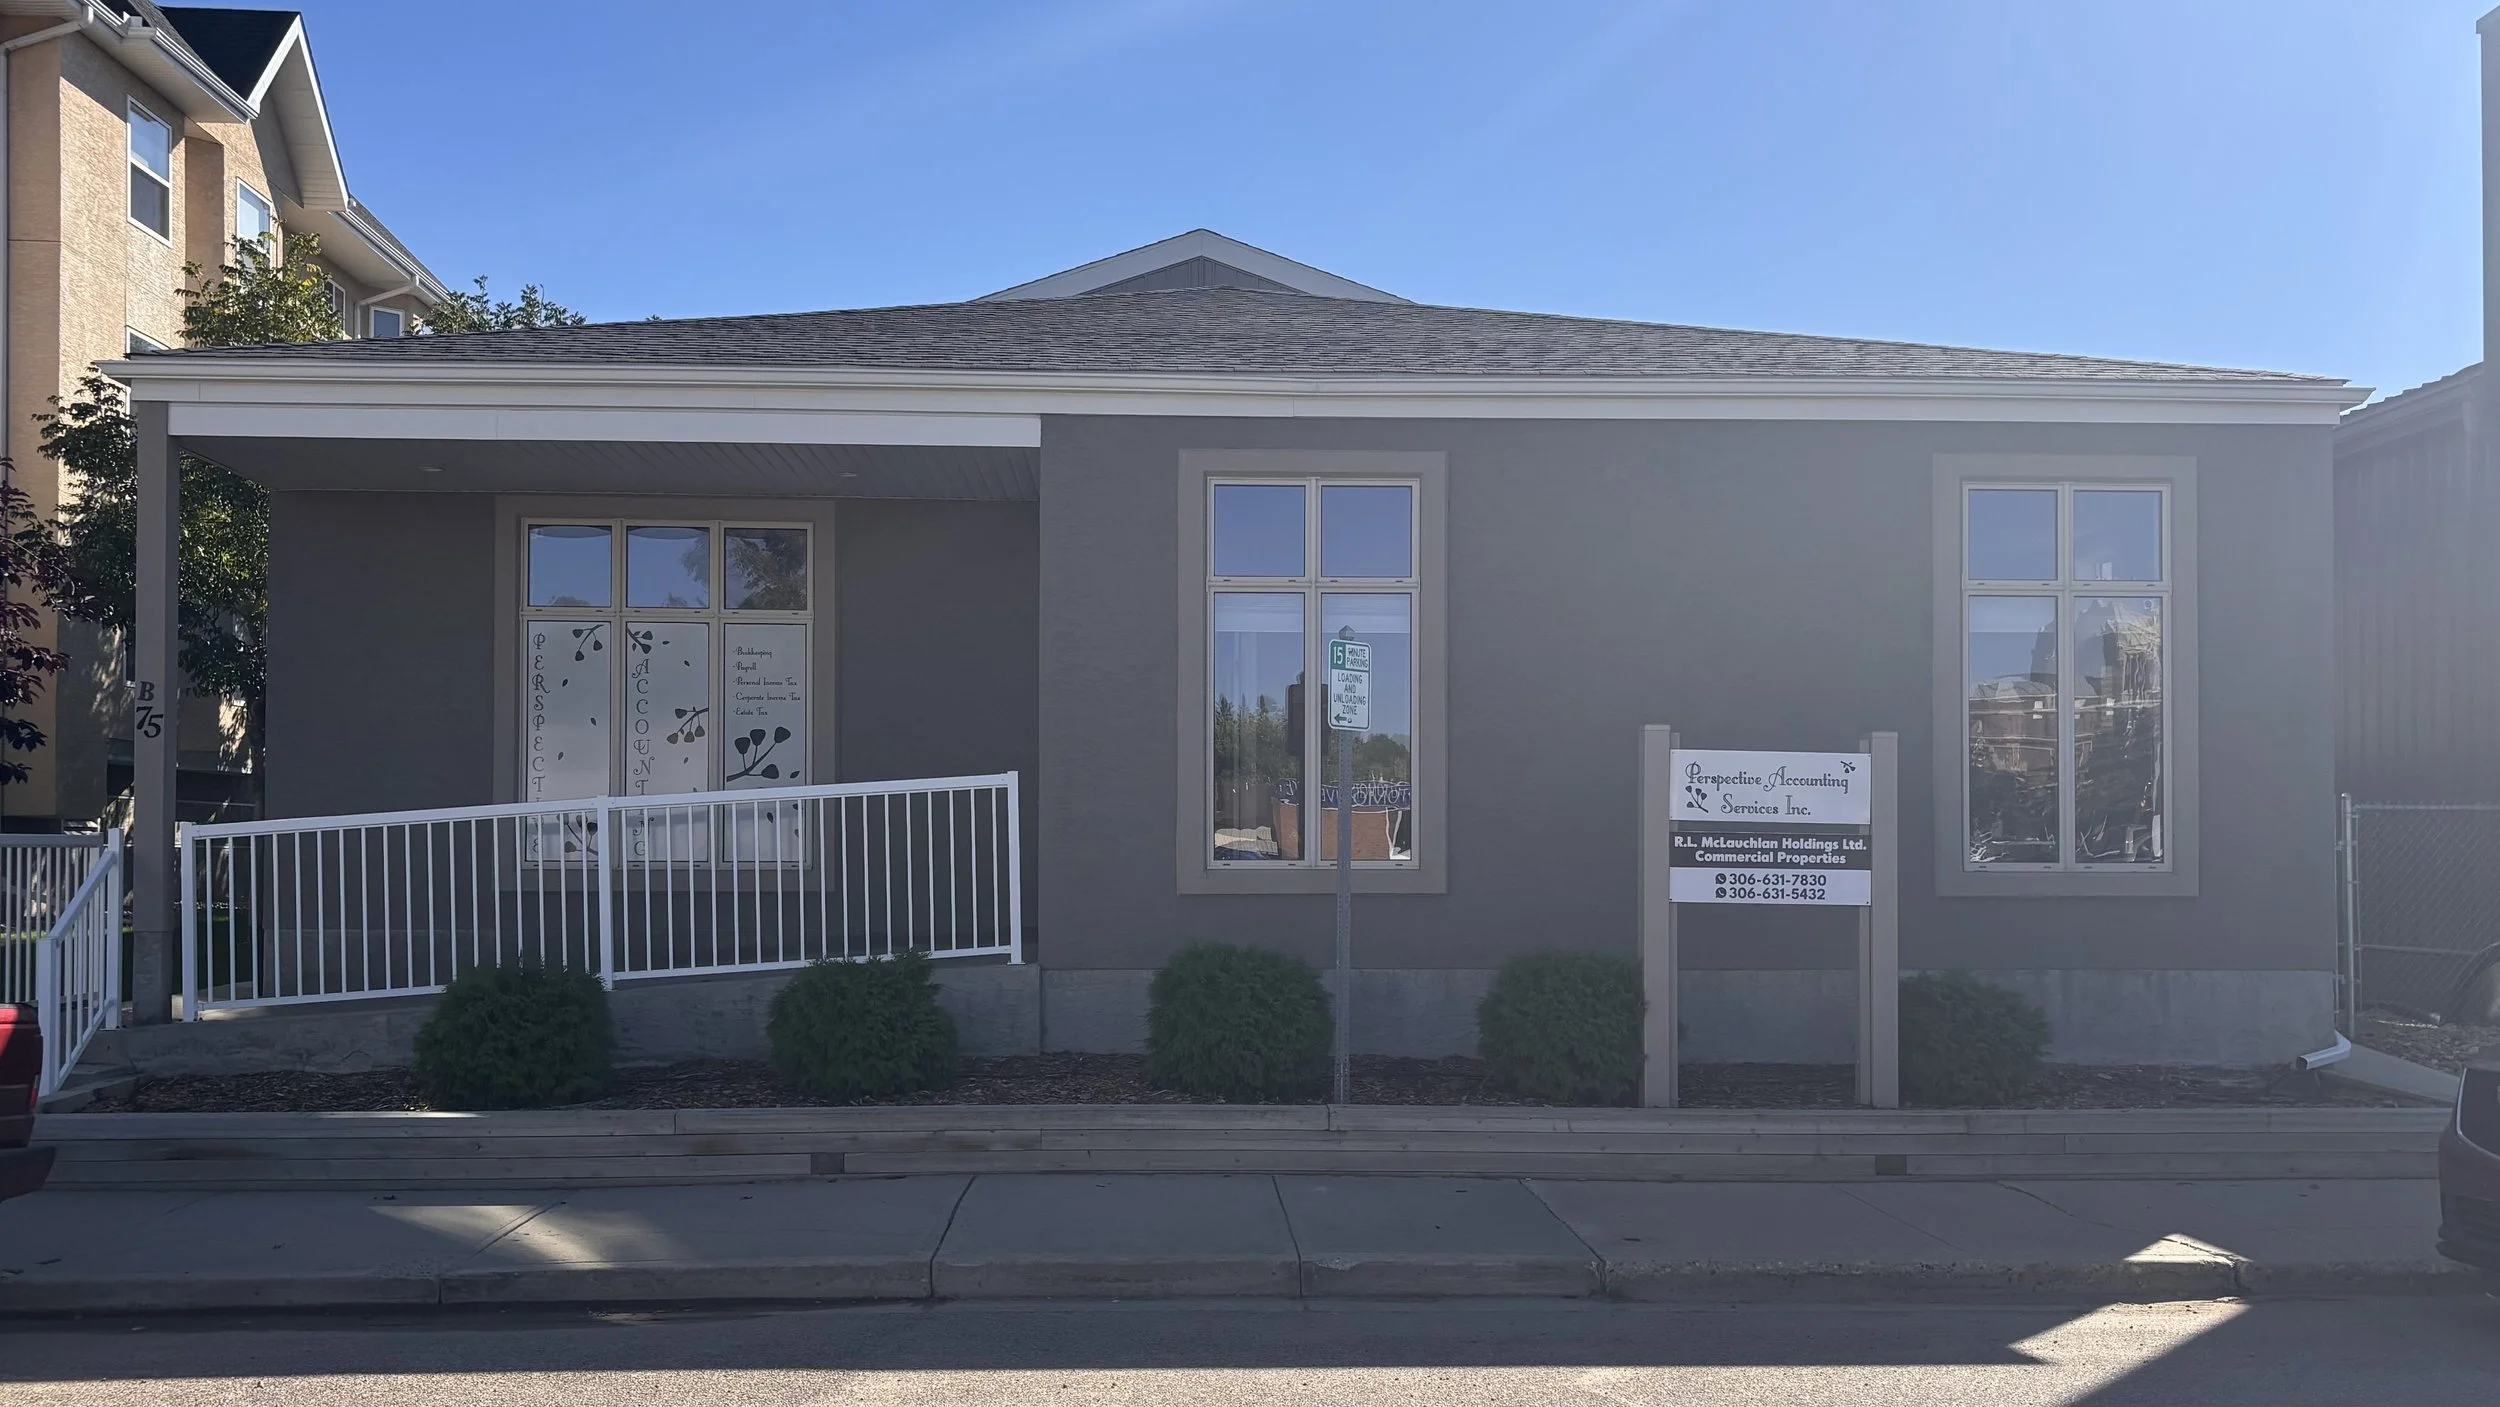
Our office is located at 75B Hochelaga St West, Moose Jaw, Saskatchewan, S6H 2E9.
Phone: 306-694-6161
Email: jbryant@peakgroup.com
Meetings available by appointment.
A comfortable place to sit down and talk things through.
Whether you’re coming in for a portfolio review, retirement planning, or simply a second opinion, we aim to make every meeting straightforward, relaxed, and easy to understand.
Our Story and What Makes us Different
We are a family-run financial planning practice built on more than 35 years of relationships, personal service, and a belief that good financial advice should be clear, approachable, and accessible.
The business was built by Jeffrey Bryant and has since transitioned to the next generation, with Josh Bryant now serving as lead advisor. As the practice has grown, we have continued to modernize the way we serve clients through more tailored advice, quicker communication, improved online access, and a more convenient overall experience.
While the way we deliver advice has evolved, the principles the business was built on have remained the same: putting clients first, taking the time to understand their needs, building long-term relationships, and providing advice they can feel confident in.
Josh works with individuals, families, retirees, professionals, and business owners to help them make sense of their investments, prepare for retirement, and make informed financial decisions as their needs change. His approach is centered on clear communication, ongoing education, and helping clients understand not only what they are invested in, but why.
As a younger advisor, Josh also brings long-term continuity to the relationships he builds. For clients approaching retirement, this can provide added confidence knowing they have an advisor who can support them through retirement and for many years beyond it.
Josh works closely with Jodi Mohr, our licensed administrative assistant, who plays an important role in client service, communication, and keeping the day-to-day experience organized, efficient, and welcoming.
Jeffrey remains involved with the practice, bringing more than 35 years of industry experience and perspective to the team. Although he is no longer licensed, his experience continues to be a valuable resource and an important part of the history and culture of the business.
As the practice continues to grow, we remain focused on providing more personalized service, faster communication, easier online access, and a better overall client experience while maintaining the same values and relationships the business was built on.
What Sets Us Apart
We believe there should never be a financial threshold to receiving thoughtful investment advice.
Whether you are setting up your first regular investment plan, building wealth for the future, preparing for retirement, or already drawing income from your investments, you should have access to guidance and the opportunity to ask questions.
Financial planning does not suddenly become important once you have accumulated a large portfolio. Good habits often start small, and having a clear plan early can make a meaningful difference over time.
We also understand that life is busy. That is why we aim to make meetings and communication as flexible and convenient as possible, while providing timely responses and easy online access whenever possible.
A Personal Approach to Financial Advice
Financial decisions can feel complicated, but getting advice shouldn’t. Our goal is to provide a comfortable and welcoming environment where you can ask questions, understand your options, and make informed decisions with confidence.
Investment & Portfolio Advice
Every portfolio starts with a conversation. We take the time to understand your goals, time horizon, risk tolerance, income needs, and overall financial picture before recommending an investment approach.
Depending on your circumstances, your portfolio may include mutual funds, ETFs where available, alternative investments, fixed income, GICs, money market investments, and other solutions available through PEAK Investment Services Inc.
The goal is not simply to own investments, but to build a portfolio with a clear purpose behind it.
Retirement & Income Planning
Retirement planning is about more than accumulating investments. We help clients think through how their investments can support their lifestyle, how withdrawals may be structured, and how investment risk may change as retirement approaches.
For clients already in retirement, we can help build an investment and income strategy designed to provide liquidity while keeping the longer-term portion of the portfolio invested appropriately.
Registered Accounts
We provide guidance across RRSPs, RRIFs, TFSAs, RESPs, FHSAs, LIRAs, and other registered accounts.
Each account has different rules and features. We help clients understand how these accounts may fit within their overall investment and retirement strategy.
Corporate & Non-Registered Investing
For business owners, incorporated professionals, and investors with assets outside registered accounts, we provide guidance on building portfolios with consideration given to growth, income, liquidity, and the tax characteristics of different investments.
Where corporate assets are involved, we can work alongside your accountant or other professional advisors so that the investment strategy can be considered within your broader financial circumstances.
Whether you are building wealth, preparing for retirement, managing corporate assets, or simply looking for a second opinion, the first step is a conversation. There is no pressure to make immediate changes. The goal is to understand where you are today and determine what makes sense moving forward.
Financial Services
How We Can Help
Investment Advice
Personalized portfolios built around your goals, time horizon, risk tolerance, and income needs.
Retirement Planning
Guidance on retirement income, withdrawals, registered accounts, and managing risk as retirement approaches.
Corporate & Non-Registered Investing
Investment strategies for business owners, incorporated professionals, and investors with assets outside registered accounts.
Registered Accounts
Support with RRSPs, RRIFs, TFSAs, RESPs, FHSAs, LIRAs, and other registered plans.
Second Opinions
A fresh review of your current investments and financial strategy, with no pressure to make immediate changes.
Investing Isn’t One-Size-Fits-All
Every financial situation is different, and the right strategy can change over time.
For one person, contributing to an RRSP may make sense because of the immediate tax deduction and long-term tax-deferred growth. For someone else, greater emphasis may be placed on a TFSA, FHSA, non-registered investments, or other available accounts depending on their circumstances.
Retirement planning often involves considering how different accounts and income sources may work together. RRSPs, RRIFs, TFSAs, CPP, OAS, pensions, and non-registered investments can all play different roles throughout retirement.
For younger investors, the focus may be different again. Time horizon, growth objectives, liquidity, contribution room, and the characteristics of TFSA, RRSP, FHSA, corporate, and non-registered accounts can all influence the investment strategy.
The goal is not simply to maximize one account. It is to build an investment and retirement strategy that reflects your current circumstances, future income needs, liquidity requirements, and long-term goals. Where tax considerations are involved, we can work alongside your accountant or tax professional as part of the planning process.
Our Process
Good advice starts with understanding where you are today and where you want to go. Our process is designed to be straightforward, personal, and easy to follow.
01 — Start With a Conversation
We begin by getting to know you, your goals, your financial situation, and what matters most to you. It is also your opportunity to ask questions and get a clear sense of how we work.
02 — Review Your Financial Picture
We take a closer look at your current investments, registered and non-registered accounts, income needs, time horizon, risk tolerance, and other factors that may affect your overall strategy.
03 — Build a Personalized Strategy
From there, we develop an investment approach tailored to your circumstances. Recommendations are based on your goals, time horizon, risk tolerance, liquidity needs, and broader financial picture.
04 — Put the Plan Into Action
Once you are comfortable with the recommendations, we help implement the strategy in an organized and thoughtful way. We take the time to explain what is being done and why.
05 — Review and Adjust Over Time
Your financial needs can change over time. We stay in touch, review your progress, and make adjustments as your goals, circumstances, and priorities evolve.
Office Hours
Monday–Friday
9:00 AM–5:00 PM
Evenings and other times available by appointment.
Meet With Us
In person, phone, and virtual meetings are available.
Our Team
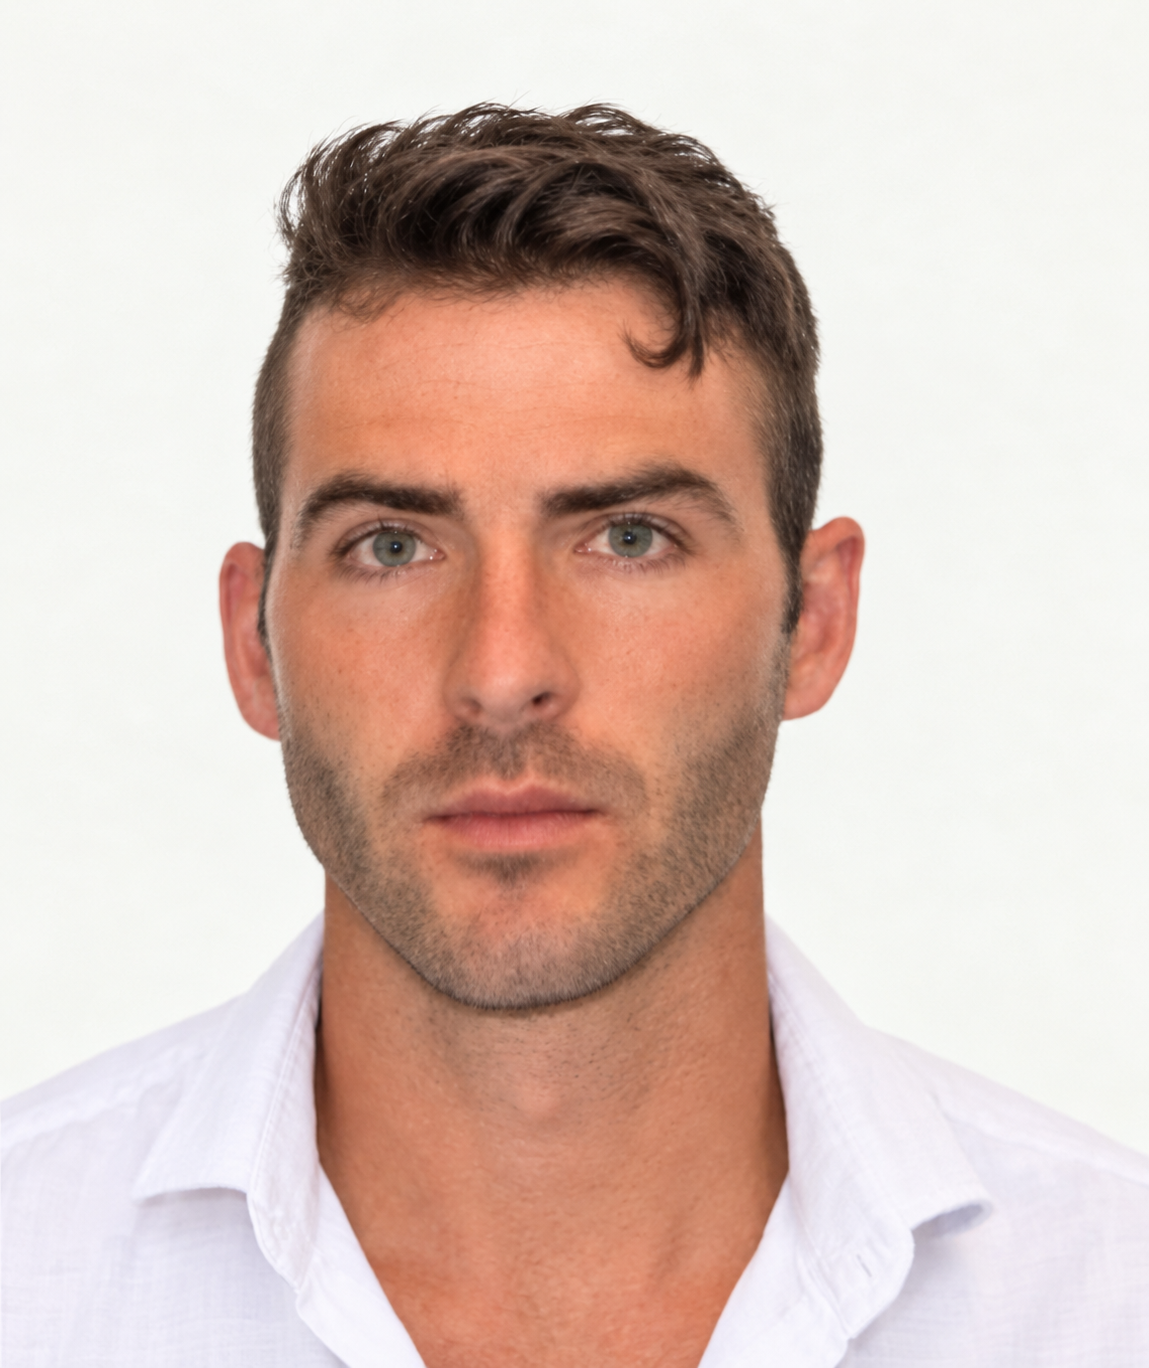
Josh Bryant
Financial Advisor
Josh serves as the lead advisor of the practice, working with individuals, families, retirees, professionals, and business owners. His focus is on providing personalized investment advice, clear communication, and long term planning that evolves alongside each client.
Outside of the office, Josh stays actively involved in the community and serves on the board of Community Futures. He believes strong relationships and community involvement are an important part of building a business that clients can feel connected to and confident in.
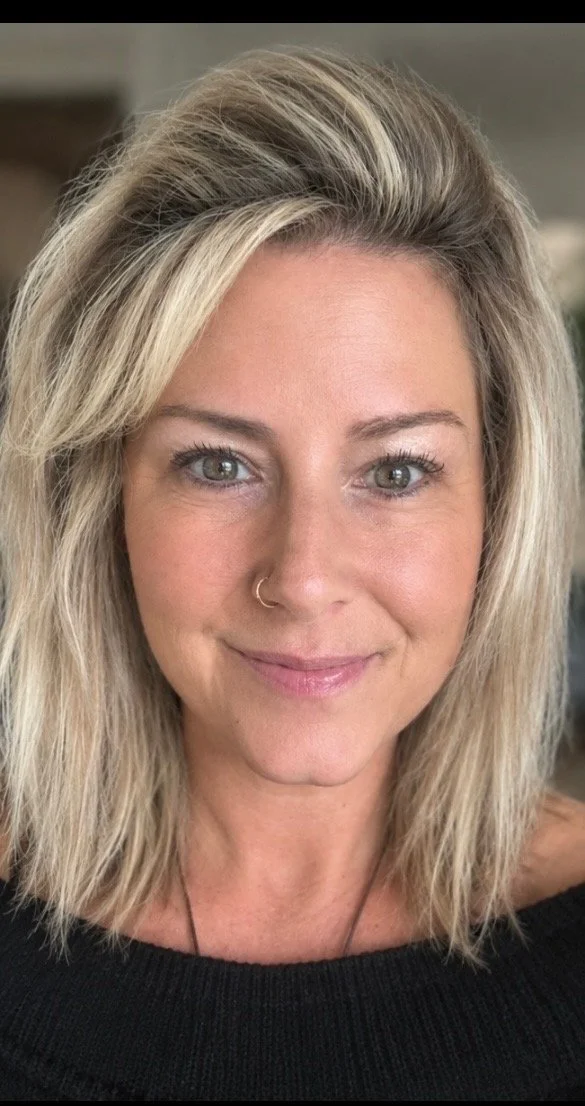
Jodi Mohr
Administrative Assistant, Registered Representative
Jodi plays an important role in client service and the day-to-day operation of the practice. She helps keep communication organized, assists clients with administrative needs, and helps ensure the overall experience is welcoming and efficient.
Jeffrey Bryant
Client Relations & Business Development
Jeffrey built the practice over more than 35 years and continues to remain involved with the business. Although he is no longer licensed and is unable to provide investment advice, his industry experience, longstanding client relationships, and perspective remain an important part of the team.
Frequently Asked Questions
-
No. We believe access to financial guidance should not be limited to people with large portfolios. Whether you are just getting started, building wealth, or preparing for retirement, we are happy to have a conversation and determine how we may be able to help.
-
If possible, bring recent investment statements, pension information, and any other financial documents you feel are relevant. The goal of the first meeting is simply to understand your current situation, your goals, and any questions or concerns you may have.
-
No. There is no pressure to make immediate changes. We can review your current investments, discuss what is working well, identify areas that may need attention, and help you understand your options before any decisions are made.
-
Yes. We work with clients who are preparing for retirement as well as those who are already retired. This can include investment strategy, retirement income planning, registered accounts, withdrawals, and managing risk as your needs change.
-
Yes. Meetings are available in person, by phone, or virtually. We aim to make communication and meetings as convenient as possible.
Account Types
-
A TFSA is a flexible account that can be used for saving or investing. Contributions are made with after-tax dollars, so you do not receive a tax deduction when you contribute. However, investment growth and withdrawals are generally tax-free. TFSAs can be used for retirement, a home purchase, emergency savings, or other financial goals.
-
An RRSP is designed primarily for retirement savings. Contributions may reduce your taxable income in the year they are made, while withdrawals are generally taxable as income. Investments inside the account can grow on a tax deferred basis until money is withdrawn.
-
An FHSA is designed to help eligible first-time home buyers save for a qualifying home purchase. Contributions may be tax-deductible, and qualifying withdrawals for a first home are tax-free. If the funds are not used to purchase a home, the remaining balance can generally be transferred to an RRSP or RRIF without immediate tax consequences and without using existing RRSP contribution room.
-
An RESP helps families save for a child’s post-secondary education. Contributions are not tax-deductible, but the government may provide a 20% Canada Education Savings Grant (CESG) on the first $2,500 contributed each year, up to $500 annually. If unused grant room is available, up to $1,000 of CESG may be received in a year. The lifetime CESG maximum is $7,200 per beneficiary, and the lifetime RESP contribution limit is $50,000 per beneficiary.
Canada Education Savings Grant (CESG) - Canada.ca
Registered Education Savings Plans and related benefits - Canada.ca
-
A RRIF is used to turn retirement savings into income. An RRSP must be converted to a RRIF, annuity, or withdrawn by the end of the year you turn 71. Once a RRIF is established, you must withdraw at least a minimum amount each year beginning the following year. The minimum withdrawal is based on your age and the value of the RRIF at the beginning of the year, and the required percentage increases as you get older. Withdrawals are taxable as income.
-
A non-registered investment account has no contribution limit and offers more flexibility than registered accounts, but investment income earned in the account may be taxable.
Tax efficiency can be improved by choosing investments that generate fewer taxable distributions or by favouring investments that produce more capital growth rather than frequent interest or income payments. Depending on the investment, this may help defer taxes until an investment is sold and can reduce the amount of taxable income reported each year.
Because different types of investment income are taxed differently, the investments held in a non-registered account should be selected with both investment goals and tax efficiency in mind.
Start the conversation
Tell us a little about your goals and we’ll reach out within one business day.